Chase Freedom Flex vs Freedom Unlimited: Which One Should You Get?
Chase's two no-annual-fee cash back cards are among the most popular in the US — and they're frequently confused. The names sound similar, the designs look alike, and both earn Chase Ultimate Rewards points. But they work very differently. This guide breaks down the real differences and tells you which one makes more sense for your spending.
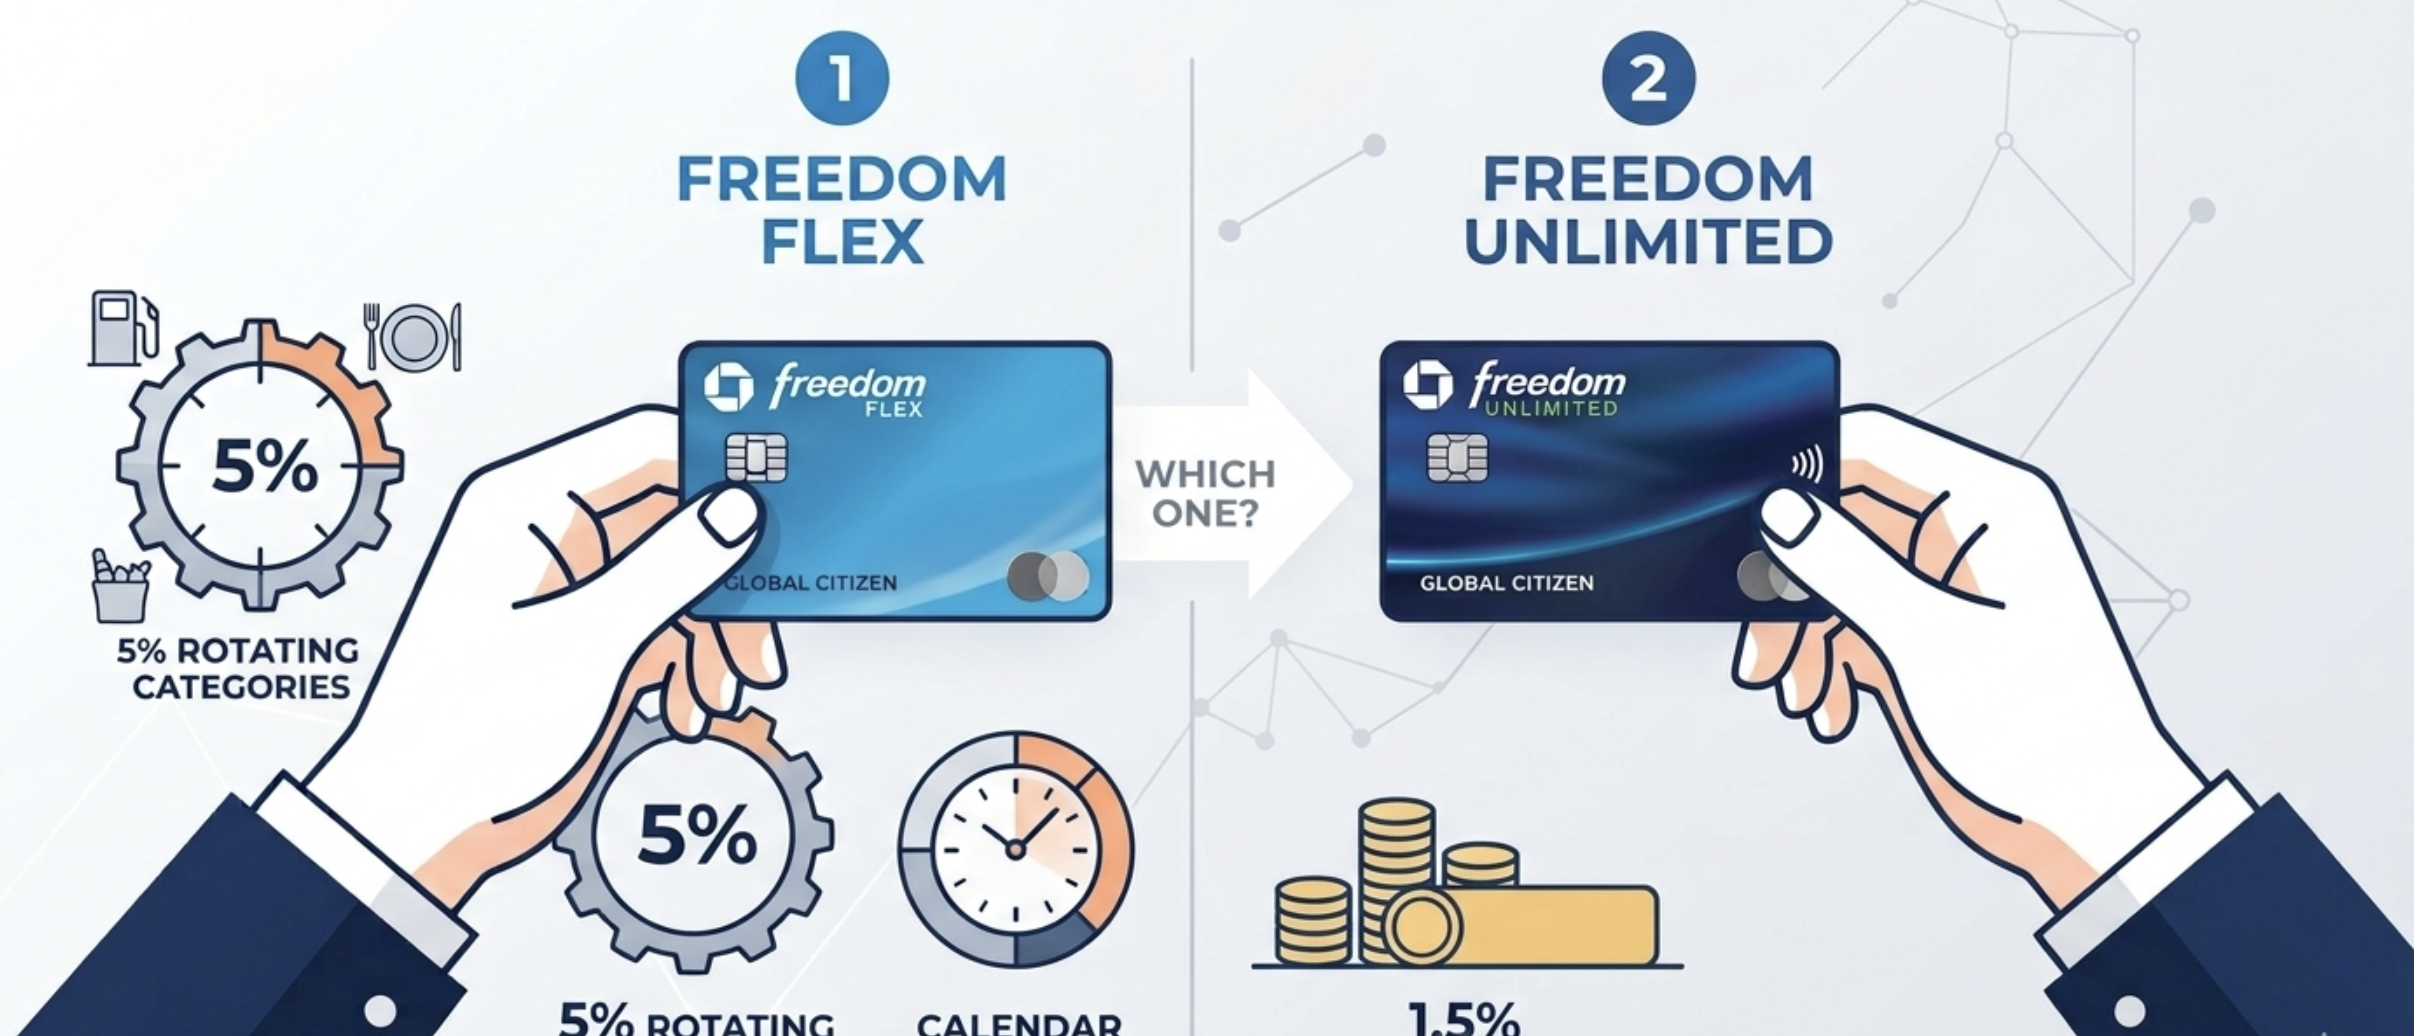
Chase Freedom Flex or Freedom Unlimited? Both have no annual fee, but they reward spending very differently. This side-by-side comparison helps you decide which fits your spending habits.
Chase's two no-annual-fee cash back cards are among the most popular in the US — and they're frequently confused. The names sound similar, the designs look alike, and both earn Chase Ultimate Rewards points. But they work very differently.
This guide breaks down the real differences and tells you which one makes more sense for your spending.
Quick Comparison
Feature | Freedom Flex | Freedom Unlimited |
|---|---|---|
Annual fee | $0 | $0 |
Base rate | 1% on most purchases | 1.5% on most purchases |
Dining | 3% | 3% |
Drugstores | 3% | 3% |
Travel via Chase portal | 5% | 5% |
Rotating 5% categories | Yes (up to $1,500/quarter) | No |
Rewards type | Chase Ultimate Rewards | Chase Ultimate Rewards |
Intro APR | 0% for 15 months | 0% for 15 months |
Foreign transaction fee | 3% | 3% |
The Core Difference: Rotating Categories vs Flat Rate
This is the decision that matters.
Freedom Flex gives you 5% cashback on rotating quarterly categories — things like grocery stores, gas stations, PayPal, Amazon, or streaming services. The catch: you have to activate the bonus each quarter, and it's capped at $1,500 in spending ($75 max bonus per quarter).
Freedom Unlimited gives you a flat 1.5% on everything, with no activation required and no cap. Simple.
When Freedom Flex Wins
The Flex is better if:
You spend heavily in whichever categories Chase rotates in (historically: Amazon Q4, grocery stores Q1, gas stations Q2)
You're willing to track and activate quarterly bonuses
You're pairing it with a premium Chase card (Sapphire Preferred/Reserve) to transfer points
Example calculation: If you spend $1,500 in a 5% quarter + $500 at restaurants + $200 at drugstores:
5% × $1,500 = $75
3% × $500 = $15
3% × $200 = $6
1% × remaining spend
Total on bonus categories: ~$96 per quarter just from the rotating bonus
When Freedom Unlimited Wins
The Unlimited is better if:
You want simplicity — no activation, no tracking
Your spending doesn't match the rotating categories
You spend a lot outside of specific categories (bills, subscriptions, etc.)
You're new to credit cards and want a straightforward product
Example: $3,000/month in total spending, mostly miscellaneous:
Freedom Unlimited: $3,000 × 1.5% = $45/month = $540/year
Freedom Flex: $3,000 × 1% = $30/month base = $360/year (without hitting bonus categories)
The Unlimited wins clearly when your spending is spread out.
Both Cards Share These Benefits
3% at restaurants — dining out earns the same on both
3% at drugstores — CVS, Walgreens, Rite Aid
5% on Chase Travel — booked through the Chase Ultimate Rewards portal
0% intro APR for 15 months on purchases and balance transfers
No annual fee — forever, not just the first year
Purchase protection and extended warranty
Trip cancellation/interruption insurance
The Ultimate Rewards Angle
Both cards earn Chase Ultimate Rewards points, which are worth 1 cent each for cash back. But here's the key insight for people with multiple Chase cards:
If you also have a Chase Sapphire Preferred ($95/year) or Sapphire Reserve ($550/year), you can transfer your Freedom points to the Sapphire card's pool — where they become worth 1.25–1.5 cents each toward travel, or can be transferred to airline and hotel partners.
This makes both Freedom cards significantly more valuable as part of a Chase ecosystem.
For New Immigrants Specifically
Both cards require good credit (typically 670+ FICO). If you're in your first year of building US credit, you'll likely need to start with a secured card first.
Once you've established a credit history, the Freedom Unlimited is usually the easier approval. Its flat-rate structure also suits people who are still learning the US credit card landscape.
Important: Both cards charge a 3% foreign transaction fee. If you frequently send money abroad or travel internationally, consider a no-FX-fee card instead.
Our Recommendation
Get Freedom Unlimited if:
You want simplicity
Your spending is varied and hard to predict
You're just starting with Chase cards
Get Freedom Flex if:
You're organized and willing to activate quarterly
Your spending aligns well with rotating categories (Amazon, groceries, gas)
You already have a Sapphire card and want to maximize points
Get both if:
You're building a Chase ecosystem — many experienced users carry both and route spending to whichever earns more in a given category
Summary
Neither card is objectively better — it depends on your spending habits and how much effort you want to put in. The Freedom Unlimited wins on simplicity and consistent returns. The Freedom Flex wins when you maximize the quarterly bonuses.
If you can only choose one: Freedom Unlimited is the safer default.
Annual percentage rates, rewards structures, and card benefits are accurate as of 2026. Chase may change terms at any time — verify current offers at chase.com before applying. ClearFinLab does not accept paid rankings or sponsored placements.